DMCI Homes now accepts Pag-IBIG Fund housing loans for the balance on its ready-for-occupancy condos — Allegra Garden Place (Pasig), The Oriana and The Erin Heights (Quezon City), Anissa Heights (Pasay) and 12 more projects on DMCI’s approved list, below. It joins spot cash, bank financing and DMCI in-house financing as a fourth way to pay.
Pag-IBIG lends up to ₱10 million for up to 30 years. Until December 31, 2026 it is running promotional rates of 4.5% on loans up to ₱4.9 million and 5.75% above that, fixed for three years. On a real Allegra studio that is ₱23,201 a month — about ₱13,321 less than the same unit on a typical bank loan.
Pag-IBIG has its own DMCI payment terms (memo PD-26-10-024): a 12% downpayment over 18 months on ready-for-occupancy units, with no regular 1% discount but ₱10,000 off until December 31, 2026. Every rule, project by project →
For years, whenever a buyer asked me “Can I use my Pag-IBIG?” I gave the same answer: DMCI is spot cash, bank or in-house. Pick one.
That answer just changed. DMCI Homes has made Pag-IBIG financing official on 16 projects — Allegra Garden Place, The Oriana, Anissa Heights, 11 of its Legacy Projects and, while it is still being built, The Erin Heights.
This matters more than any discount I have announced this year, because of who it reaches. Every employed Filipino pays into Pag-IBIG. Every OFW has been required to since 2009. Millions of people have years of contributions sitting in the Fund, and until now, none of it could touch a DMCI unit.
I am Belle Aldea, DMCI Homes Property Consultant. Below is what changed, which units it applies to today, what it does to your monthly — computed on real units from DMCI’s October 2026 availability list — and the one Pag-IBIG rule that can quietly cost you ₱4,000 a month if nobody points it out.
DMCI memo PD-26-10-024 sets the terms for Pag-IBIG buyers: 12% over 18 months on ready-for-occupancy units, over up to 32 months at The Erin Heights and The Oriana South Tower, 20% until turnover at Anissa Heights. No regular 1% on the 12% term; the Legacy 20% still applies; every Pag-IBIG buyer gets ₱10,000 off until December 31, 2026; closing fees are paid before the loan is released. Every figure below is on those terms. Full breakdown: DMCI Pag-IBIG Financing Guidelines.
Which DMCI Projects Accept Pag-IBIG
Three groups, and they work slightly differently.
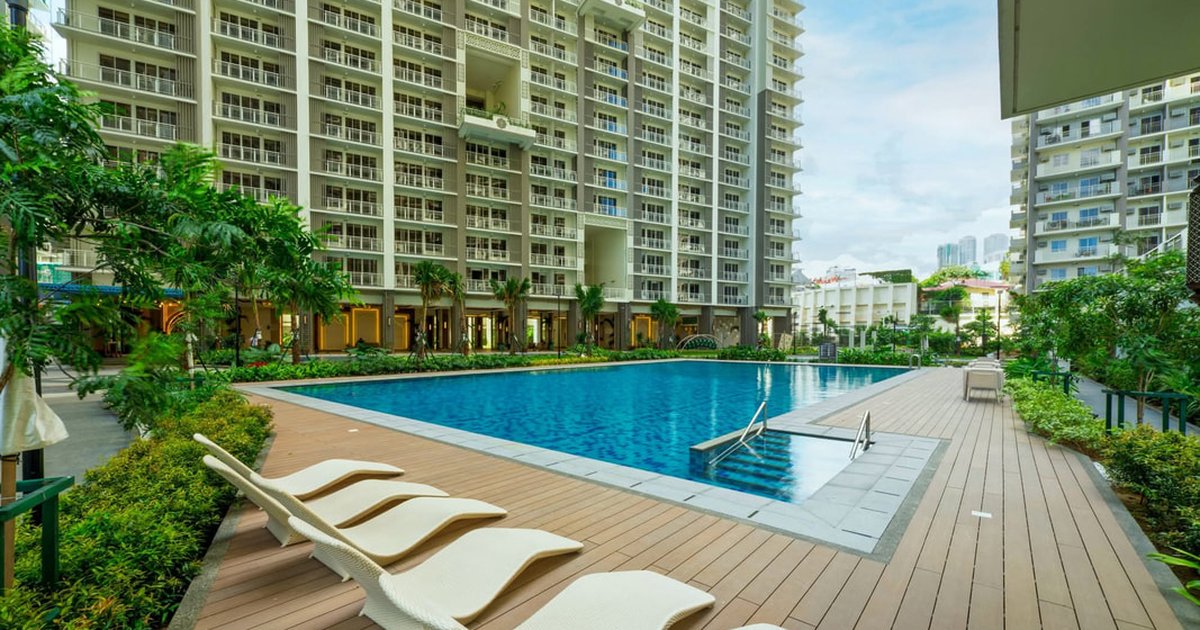
Every project on DMCI’s Pag-IBIG list
DMCI’s list (memo PD-26-10-024) has 16 projects. Most of the ones beyond Allegra, The Oriana and The Erin Heights are Legacy Projects. Their 20% Legacy discount (until November 30, 2026) applies with Pag-IBIG too: a Legacy unit is 12% over 18 months with the 20% off, plus ₱10,000. Pag-IBIG applies only to the projects on this list:
Why This Is Big News for OFWs — and Everyone Who Pays Pag-IBIG
Pag-IBIG is not something most people chose. It comes off the payslip — usually ₱200 a month, matched by the employer — and for overseas Filipino workers it has been mandatory since Republic Act 9679 took effect in 2010. Which means if you have worked for even two years, you very likely already qualify on the contribution count. The Fund asks for 24 monthly contributions.
For an OFW, three things make this better than a bank:
- You are already a member. There is no new relationship to build with a lender who does not know you; your contribution record is the relationship.
- The monthly is lower — a lower rate and a longer term, which is exactly what you need when you are budgeting a home in pesos on a salary earned somewhere else.
- You do not need to fly home. A family member here signs for you under a Special Power of Attorney, and I run the DMCI side of the file — reservation, downpayment schedule, documents and turnover.
“If you have been paying Pag-IBIG for years and wondering what you were paying for — this is it.”
Pag-IBIG vs Bank: The Same Unit, Side by Side
Two real, available two-bedrooms, each computed both ways. The Pag-IBIG route is on DMCI’s Pag-IBIG terms (memo PD-26-10-024): 12% over 18 months with no regular 1%, plus the ₱10,000 Pag-IBIG special discount — Allegra keeps the Christmas Countdown’s 1.5%. The bank route is on DMCI’s regular terms: 12% over 32 months with the 1%.
Allegra Garden Place · Soraya 309 · 2BR, 55 sqm · ₱7,748,000
| Pag-IBIG route | Bank route | |
|---|---|---|
| Discount | 1.5% + ₱10,000 Countdown + Pag-IBIG special | 1% + 1.5% regular + Countdown |
| Net price | ₱7,621,780 | ₱7,555,462 |
| 12% downpayment | ₱49,145/mo × 18 | ₱27,395/mo × 32 |
| Balance to finance (88%) | ₱6,707,166 | ₱6,648,807 |
| Loan / month | ₱39,340 5.75% · 30 yrs | ₱53,834 7.5% · 20 yrs |
| Monthly difference | ₱14,421 less | |
| Gross household income to carry it (30% of gross income) | ₱130,471 | ₱178,541 |
The Oriana · North 405 · 2BR, 54.5 sqm · ₱7,501,000
| Pag-IBIG route | Bank route | |
|---|---|---|
| Discount | ₱10,000 Pag-IBIG special | 1% |
| Net price | ₱7,491,000 | ₱7,425,990 |
| 12% downpayment | ₱48,273/mo × 18 | ₱26,910/mo × 32 |
| Balance to finance (88%) | ₱6,592,080 | ₱6,534,871 |
| Loan / month | ₱38,470 5.75% · 30 yrs | ₱52,644 7.5% · 20 yrs |
| Monthly difference | ₱14,174 less | |
| Gross household income to carry it (30% of gross income) | ₱128,232 | ₱175,482 |
List prices from DMCI’s availability list, October 2026; computed October 21, 2026. Income rows use Pag-IBIG’s 30% rule for both routes; each bank sets its own ratio. Bank shown at an indicative 7.5% fixed over 20 years — the range most buyers are being quoted after the September rate hike. Your actual rate is set at approval.
The last row is the one I would read twice. Qualifying for a loan is about whether the monthly fits your income. On the Allegra 2BR, the bank route needs roughly ₱178,541 a month in household income; Pag-IBIG needs about ₱130,471. For a lot of families, that is the difference between “not yet” and “yes.”
The honest part
The Pag-IBIG route costs something on the way in. On the Allegra 2BR you give up the regular 1% (₱66,318 on the price, after the ₱10,000 special) and pay the downpayment over 18 months instead of 32 — ₱49,145 a month instead of ₱27,395. Some of the monthly gap is also the extra ten years: on the bank’s 20-year term the Pag-IBIG loan is ₱47,090 a month, still ₱6,472 less from the rate alone. And a 30-year loan pays interest for longer: about ₱14,090,760 over 30 years versus ₱12,854,880 over 20. Pag-IBIG wins on the monthly and on qualifying. If you can afford to pay more than the minimum, tell me — I will show you how to structure it so you also win on the total.
The ₱4.9 Million Line Nobody Will Tell You About
Pag-IBIG’s two promo rates are split by loan size: 4.5% up to ₱4.9 million, 5.75% above it. Which means a buyer who is only a little over the line pays the higher rate on the whole loan.
Allegra Garden Place, Amina 919 — a 30 sqm one-bedroom at ₱5,710,000. On DMCI’s Pag-IBIG 12% term the balance is ₱4,940,628. That is ₱40,628 over the line, so it prices at 5.75%: ₱28,979 a month.
Pay that ₱40,628 as extra downpayment. The loan drops to exactly ₱4,900,000, it qualifies for 4.5%, and the monthly falls to ₱24,828 — ₱4,004 a month less, or ₱144,144 over the three-year fixed period, for ₱40,628 paid upfront.
Same story at Cypress Towers (Legacy): Celesta PH10 leaves a ₱4,942,432 balance — ₱42,432 over the line — and pulling it under saves ₱4,015 a month. When I compute your unit, this is the first thing I check, and my computation sheet now flags it on every Pag-IBIG card. Confirm the bracket on your own loan with Pag-IBIG when you file; I will go through it with you.
Allegra Garden Place, Pasig
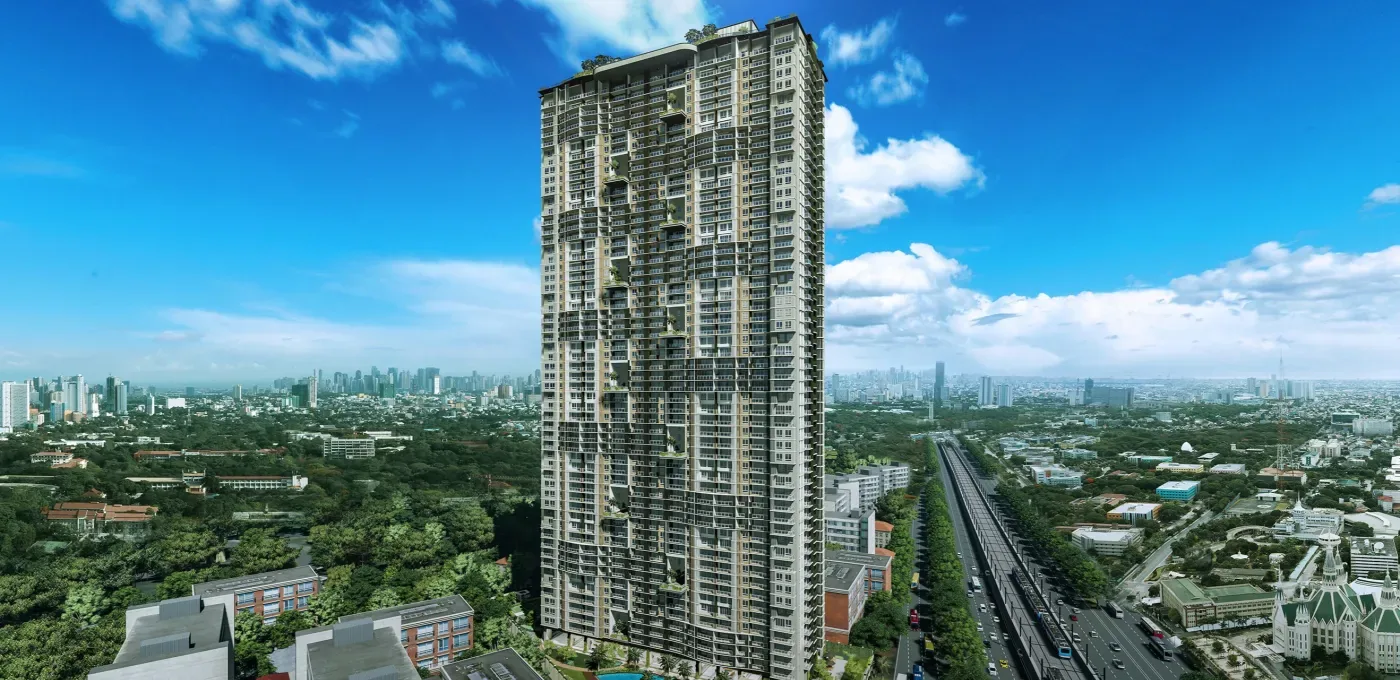
Two 55-storey Modern Moroccan towers — Amina and Soraya — on Pasig Boulevard, 110 metres from Rizal Medical Center, 3.3 km from Ortigas Center. Both towers are finished and turned over, and DMCI’s October 2026 list shows 753 units open, from studios to three-bedrooms.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| Soraya 2417 · Studio · 30 sqm | ₱5,266,000 | ₱23,201 4.5% | ₱36,589 |
| Amina 919 · 1BR · 30 sqm | ₱5,710,000 | ₱28,979 5.75% | ₱39,674 |
| Soraya 309 · 2BR · 55 sqm | ₱7,748,000 | ₱39,340 5.75% | ₱53,834 |
Pag-IBIG column on DMCI’s Pag-IBIG terms: 12% over 18 months, Christmas Countdown 1% (no regular 1%) plus the ₱10,000 Pag-IBIG special discount. Bank column on the regular terms: 12% over 32 months, 1% + 1%, then an indicative 7.5% over 20 years.
The studio is the headline: a finished, move-in-ready Pasig address on a Pag-IBIG loan of ₱23,201 a month. On the Pag-IBIG route its 12% downpayment runs 18 months — ₱33,022 a month — and the Christmas Countdown’s 1.5% (1% in November) is already in these figures.
The Oriana, Quezon City
A 54-storey tower on Aurora Boulevard, Project 4 — 390 metres to LRT-2, with Anonas, Katipunan and Cubao stations minutes away. The North Tower is ready for occupancy: Pag-IBIG buyers pay 12% over 18 months. The South Tower turns over in November 2027: 12% over up to 32 months. Neither tower takes a % discount on the Pag-IBIG 12% term (The Oriana is outside the Christmas Countdown); both get the ₱10,000 Pag-IBIG special discount. 334 North Tower two-bedrooms are open on DMCI’s October 2026 list.
| Unit | List price | Pag-IBIG / mo | Bank / mo |
|---|---|---|---|
| North 1906B · 1BR · 29 sqm | ₱5,109,000 | ₱22,736 4.5% | ₱35,857 |
| North 405 · 2BR · 54.5 sqm | ₱7,501,000 | ₱38,470 5.75% | ₱52,644 |
| South MZ09 · Studio · 30 sqm | ₱5,222,000 | ₱28,240 6.25% | ₱36,650 |
North 1906B is the only one-bedroom left in the North Tower. On Pag-IBIG it is ₱22,736 a month, and the balance sits under the ₱4.9 million line, so it gets the 4.5% rate without any adjustment. South Tower loans are filed after turnover, so I quote them at Pag-IBIG’s regular 6.25%.
The Legacy Projects: the 20% and Pag-IBIG
DMCI’s Pag-IBIG terms settle the question I was asked most this week: the Legacy 20% discount applies with Pag-IBIG too. With Pag-IBIG financing, a Legacy unit is a 12% downpayment over 18 months with the 20% off (memo PD-26-05-026, until November 30, 2026), plus the ₱10,000 Pag-IBIG special discount until December 31, 2026.
So on a Legacy unit you no longer choose between the lower price and the lower monthly: Pag-IBIG gives you both. These are the units open on DMCI’s October 2026 list:
| Community · unit | List price | Bank route: after 20% | Pag-IBIG route: after 20% + ₱10,000 | Pag-IBIG downpayment |
|---|---|---|---|---|
| Mayfield Park Residences Mandala 213 · 2BR · 42 sqm · Cainta | ₱4,380,000 | ₱3,504,000 ₱24,841/mo bank | ₱3,494,000 ₱15,579/mo · 4.5% | ₱21,627/mo × 18 |
| Raya Garden Condominiums Surabaya 432 · Studio · 31 sqm · Parañaque | ₱4,303,000 | ₱3,442,400 ₱24,404/mo bank | ₱3,432,400 ₱15,304/mo · 4.5% | ₱21,216/mo × 18 |
| Maricielo Villas Almeria 513 · 2BR · 56.5 sqm · Las Piñas | ₱6,224,000 | ₱4,979,200 ₱35,299/mo bank | ₱4,969,200 ₱22,157/mo · 4.5% | ₱31,461/mo × 18 |
| Alea Residences Budi 304 · 2BR · 55 sqm · Bacoor, Cavite | ₱6,643,000 | ₱5,314,400 ₱37,675/mo bank | ₱5,304,400 ₱23,651/mo · 4.5% | ₱33,696/mo × 18 |
| Rhapsody Residences Viola 302 · 2BR · 55.5 sqm · Muntinlupa | ₱6,855,000 | ₱5,484,000 ₱38,877/mo bank | ₱5,474,000 ₱24,408/mo · 4.5% | ₱34,827/mo × 18 |
| Cypress Towers Celesta PH10 · 2BR · 48 sqm · Taguig (C-5) | ₱7,033,000 | ₱5,626,400 ₱39,887/mo bank | ₱5,616,400 ₱28,843/mo · 5.75% | ₱35,776/mo × 18 |
| East Raya Gardens Banyan 116 · 2BR · 62.5 sqm · Pasig | ₱7,388,000 | ₱5,910,400 ₱41,900/mo bank | ₱5,900,400 ₱30,301/mo · 5.75% | ₱37,669/mo × 18 |
| Alea Residences Raja 711 · 3BR · 85.5 sqm · Bacoor, Cavite | ₱9,243,000 | ₱7,394,400 ₱52,421/mo bank | ₱7,384,400 ₱37,922/mo · 5.75% | ₱47,563/mo × 18 |
Bank route: 20% Legacy Projects special discount per DMCI memo PD-26-05-026, units only, until November 30, 2026; 12% over 32 months, then an indicative 7.5% bank loan over 20 years. Pag-IBIG route: the same 20%, plus the ₱10,000 Pag-IBIG special discount (until December 31, 2026), 12% over 18 months (DMCI memo PD-26-10-024), Pag-IBIG over 30 years. Tivoli Garden Residences has no open units on the current list — legacy units resurface on DMCI’s reopened lists, so ask me.
The pattern holds on every unit. On the Mayfield Park two-bedroom, Pag-IBIG is ₱10,000 cheaper on the price and ₱15,579 a month against ₱24,841 on the bank loan. What it asks of you is the shorter downpayment: ₱21,627 a month over 18 months instead of ₱12,203 over 32. The 20% ends November 30, so reserve before then either way.
The Erin Heights: Pay the Downpayment Now, Pag-IBIG Later
The Erin Heights is still being built — 66% complete as of July 2026, turnover scheduled for October 2027 — on Commonwealth Avenue corner Tandang Sora, 1.1 km from UP Diliman. It works differently: you pay the 12% downpayment over up to 32 months (DMCI allows 18 to 32), and Pag-IBIG takes out the 88% balance after that. Erin keeps the Christmas Countdown on the Pag-IBIG term — 1.5% off in October, 1% in November — as its only % discount, plus the ₱10,000 Pag-IBIG special discount.
| Unit | List price | Downpayment / mo | Pag-IBIG / mo (6.25%) |
|---|---|---|---|
| Erin 3103 · Studio · 28.5 sqm | ₱5,391,000 | ₱18,938 | ₱28,718 |
| Erin 704 · 2BR · 48.5 sqm | ₱7,434,000 | ₱26,484 | ₱39,621 |
| Erin 601 · 3BR · 84 sqm | ₱11,264,000 | ₱40,631 | ₱60,062 |
One honest caveat: the 4.5% and 5.75% promo rates are for applications filed until December 31, 2026, and your Erin Heights loan is filed later. So I have computed it at 6.25% — Pag-IBIG’s rate before the promo — rather than promise you a rate that may not exist by then. If Pag-IBIG extends the promo, your monthly only goes down. The 3BR loan (₱9,754,835) also sits inside the ₱10 million cap.
Do You Qualify?
- 24 monthly contributions posted — check them on Virtual Pag-IBIG.
- Age: 65 or younger when you apply, and 70 or younger when the loan matures (so a 50-year-old can take up to 20 years).
- Income that carries the monthly — Pag-IBIG caps the amortization at 30% of gross monthly income on loans above ₱1.25 million. Co-borrowers can be combined.
- No foreclosed, cancelled or bought-back Pag-IBIG housing loan in your name.
- Loan within ₱10 million and within Pag-IBIG’s appraisal of the unit.
How to Buy a DMCI Unit With Pag-IBIG Financing
- Send me your contribution count and budget. I match you to units and compute Pag-IBIG against the bank on each — including the ₱4.9M line check.
- Reserve with ₱30,000. The unit comes off the market and your price is locked.
- Pay the downpayment on DMCI’s Pag-IBIG schedule. 12% over 18 months at Allegra, The Oriana North Tower and the Legacy Projects; over up to 32 months at The Erin Heights and The Oriana South Tower; 20% until turnover at Anissa Heights.
- File your Pag-IBIG housing loan — early. I prepare the DMCI documents Pag-IBIG asks for; OFWs file through a Special Power of Attorney. Once Pag-IBIG approves, you may finish the downpayment sooner with no restructuring fee.
- Pag-IBIG appraises and approves. It values the unit, approves your loan and issues its approval and guaranty to DMCI.
- Pay the closing fees, then Pag-IBIG releases the loan. Closing fees are not part of the Pag-IBIG loan, so they are settled first. On the release you start paying Pag-IBIG instead of DMCI, and DMCI turns over the unit and any parking bought with it.
What Pag-IBIG Financing Doesn’t Do
Good to know
- Lower monthly and easier to qualify than most bank loans.
- Works with the Christmas Countdown on Allegra and The Erin Heights — 1.5% off in October, 1% in November.
- Keeps the Legacy 20%, plus ₱10,000 off for every Pag-IBIG buyer until December 31, 2026.
- Contribution history counts — no new lender relationship to build.
Watch out for
- The downpayment runs 18 months on ready units — shorter than the 32-month bank term.
- No regular 1% on the Pag-IBIG 12% term at Allegra, The Erin Heights and The Oriana.
- Closing fees are not in the loan — pay them before release.
- The promo rate is fixed for 3 years, then reprices.
- Pag-IBIG lends against its own appraisal, which can come in under DMCI’s price.
- The 5% downpayment RFO promo is Chinabank/BPI only.
Questions I’m Getting About Pag-IBIG at DMCI
Sources
- DMCI Pag-IBIG payment terms — DMCI Homes interoffice memorandum PD-26-10-024, “Pag-IBIG Financing Standard Payment Terms”, October 16, 2026 — explained in DMCI Pag-IBIG Financing Guidelines 2026
- Pag-IBIG Fund raises limit on housing loans to ₱10 million — Philstar, May 29, 2026
- 4.5% promotional rate on loans up to ₱4.9 million; 5.75% above, up to ₱10 million — Daily Tribune, July 8, 2026
- Promo rates valid until December 31, 2026; National Housing Expo October 19–20 with DMCI Homes participating — Daily Tribune, October 2026
- Mandatory Pag-IBIG membership for overseas Filipino workers — Republic Act No. 9679, the Home Development Mutual Fund Law of 2009
- Unit prices and availability — DMCI Homes availability list, October 2026 (recomputed October 21, 2026); Legacy discount per DMCI memo PD-26-05-026; Christmas Countdown per DMCI memo PD-26-09-031
Send me your contribution count — I’ll do the rest
Tell me how many months of Pag-IBIG you have and the project you like. I will send back the real unit, the Pag-IBIG monthly against the bank, and whether you are on the right side of the ₱4.9M line — usually within the hour.
